How Equipment Financing Helps Businesses Grow Without Draining Cash
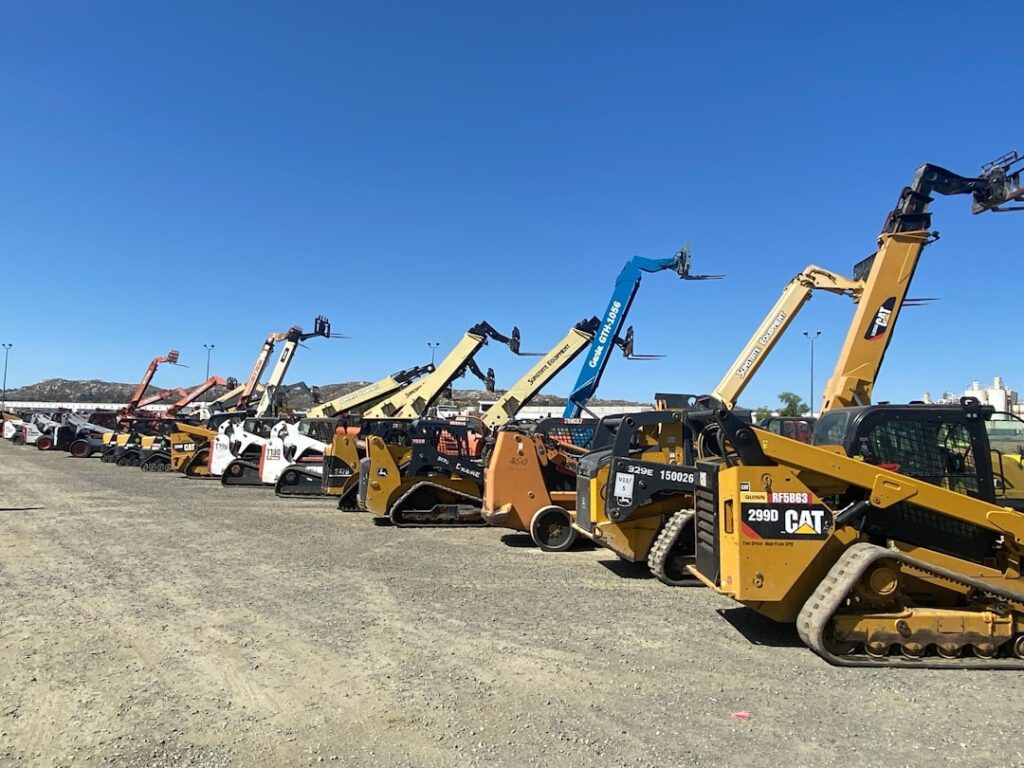
Buying new equipment can be one of the biggest challenges for a growing business. Whether it’s construction machinery, medical devices, trucks, or manufacturing tools, the cost can strain cash flow. Equipment financing through National Business Capital gives business owners a way to get what they need now while paying over time — without putting daily operations at risk. What Is Equipment Financing? Equipment financing allows a business to purchase or lease equipment and pay for it in manageable monthly payments instead of one large upfront cost. The equipment itself often serves as collateral, which can make approvals easier compared to traditional loans. This option is ideal for businesses that want to: Upgrade outdated equipment Expand operations Increase productivity Preserve working capital How National Business Capital Helps National Business Capital works with a wide network of lenders to match businesses with equipment financing options that fit their situation. Instead of approaching one lender at a time, business owners can explore multiple options through a single process. Key benefits include: Fast approvals so equipment purchases aren’t delayed Flexible terms based on the business’s cash flow Financing for new or used equipment Support from experienced funding advisors This approach helps business owners focus on growth instead of paperwork. Who Equipment Financing Is Best For Equipment financing works well for many industries, including: Construction and contracting Transportation and logistics Medical and dental practices Manufacturing and industrial businesses Landscaping and service-based companies If equipment plays a critical role in delivering your product or service, financing can be a smart growth tool. Why Partners Recommend It For referral partners like CPAs, consultants, and financial advisors, equipment financing is a practical solution to offer clients who need assets but want to protect cash reserves. It supports business expansion without increasing unnecessary financial stress. Final Thoughts Equipment financing through National Business Capital gives businesses the ability to move forward confidently — acquiring essential tools while maintaining healthy cash flow. Instead of waiting or settling for outdated equipment, business owners can invest in what they need today and pay over time. Ready to explore your options? Reach out and let’s find the right equipment financing fit for your business.
A $1 Million Surprise Bill Nearly Sank a Tesla Deal — Here’s the Financing Move That Saved It
Quick answer: When a $1 million surprise compliance cost threatened to derail a Texas manufacturer’s Tesla joint venture mid-construction, National Business Capital structured a $1.75 million term loan with a payment ramp matched to the business’s cash flow — closing the funding gap in time to keep the project on schedule. Revenue grew from $11 million to $23 million as a result. The Situation: A $1 Million Bill Nobody Budgeted For Interstate Industrial, a Texas-based battery recycling manufacturer, was deep into construction on a new facility for a major joint venture with Tesla. Late in the build — right as the project neared completion — an unexpected environmental compliance cost hit: $1 million, unplanned, and due before the facility could open. That kind of surprise doesn’t just strain a budget. It threatens the entire timeline behind a contract that took months to land. Why a Conventional Bank Wasn’t the Right Tool Here This wasn’t a creditworthiness problem. It was a timing problem — and that distinction matters more than most business owners realize. Traditional banks underwrite on their own calendar: 60, 90, sometimes 120 days from application to funded. A Tesla joint venture construction deadline doesn’t pause for that. By the time a conventional loan cleared committee, the window to finish on schedule would have closed. Interstate Industrial’s financial advisor brought in National Business Capital instead. The solution: a $1.75 million term loan structured with a payment ramp aligned to the business’s actual cash flow projections — not a rigid, one-size-fits-all amortization schedule that ignores how revenue from a new contract actually arrives. How Structuring Capital Around Cash Flow Changes the Outcome This is the part most owners miss when they think about financing: the structure of the capital matters as much as the amount. A loan that demands full payments before a new revenue stream ramps up creates exactly the kind of strain a business is trying to avoid. A structure that’s paced to match the business’s actual cash cycle does the opposite — it lets growth fund itself. The Business Outcome Construction finished on schedule. The Tesla contract commenced. Interstate Industrial’s annual revenue grew from $11 million to $23 million — more than doubling. The Takeaway for Business Owners If your business is managing a working capital gap tied to timing — not creditworthiness — the fix isn’t always “more capital.” It’s the right structure, matched to how your revenue actually arrives. That’s the difference between financing that creates pressure and financing that removes it. Michael Fieger, Partner at National Business Capital | Founder, Devil Dog Marketplace
What Is a Business Term Loan? Grow Your Business Faster [Video]
What is a business term loan, and when does it actually make sense? A short video breakdown — plus how it differs from a line of credit.
Emergency Funding vs. Bridge Capital: How to Tell Which One Your Business Actually Needs
Not every cash-flow gap means something’s wrong. Sometimes it just means the timing hasn’t caught up yet. I get calls from business owners who think they need “emergency funding,” and by the time we’ve talked it through, what they’re actually describing isn’t an emergency at all. It’s a gap they already saw coming — a retailer’s purchase order, a sale that’s 60 days from closing, inventory that has to be paid for before the season’s revenue lands. They already know the money is coming. They just need something to cover the space between now and then. What Emergency Funding Is Actually For Emergency funding exists for the moment nobody saw coming. A piece of equipment fails and stops production. A client pays 45 days late and payroll’s due Friday. Something forces a fast decision while you’re still figuring out what happened. In situations like that, speed matters more than structure — the goal is stability, not strategy. What Bridge Capital Is Actually For Bridge capital solves a different problem. The objective is already clear, and so is how it gets repaid. That could look like: Covering payroll and operating costs ahead of a receivable you’re already owed Funding inventory before a seasonal or retail sales cycle Bridging a transaction while permanent financing is being finalized Managing the timing gap between an investment and the proceeds it will generate None of that is a crisis. It’s math with a known ending — you just need the right capital to get from point A to point B without stalling out in between. The Question I Ask First Before we ever get into rates or structure, this is what I want to understand: did this catch you off guard, or did you already see it coming? That answer changes everything about what kind of funding actually fits — and it’s usually more revealing than the number itself. Why This Distinction Matters Getting this wrong costs business owners more than they realize. Treating a predictable, plannable gap like an emergency often means paying emergency-level pricing for a problem that didn’t need to be urgent. And treating a genuine emergency like a planned transaction can mean losing precious time you don’t have. At Devil Dog Marketplace, in partnership with National Business Capital, we work through both situations regularly — with the speed to move fast when something’s genuinely urgent, and the flexibility to structure something more deliberate when the timeline allows for it. Every deal we fund also contributes to Feeding America, so growing your business supports a cause bigger than the transaction itself. If you’re staring at a gap right now, ask yourself the same question I’d ask on a call: is this the surprise kind, or the kind you already saw coming? Once you know the answer, we can talk about what actually fits.
Rates Dropped. Should You Refinance Your Business Debt?
If you financed anything for your business in 2023 or 2024, you locked in a rate at the worst possible time. The Fed’s benchmark rate was sitting near its highest point in over a decade, and whatever you borrowed then, you borrowed expensive. That’s changed. The Fed cut rates three times in the second half of 2025, and the prime rate has held around 6.75% through 2026. If you’re still paying off debt from that high-rate window, there’s a real chance you’re overpaying right now — not because you did anything wrong, but because timing is timing. Why this is worth 15 minutes of your time Here’s what I’m seeing across the businesses I talk to: the reason for seeking capital has shifted. It used to be mostly about expansion — a new location, a piece of equipment, a growth bet. Now, a lot of it is about staying ahead of rising operating costs. Tariffs, wages, insurance — the day-to-day cost of running a business has climbed, and cash flow is the thing owners are protecting first. If that’s you, and you’re also sitting on debt from 2023 or 2024, you may be solving the same problem twice: tight cash flow today, plus a legacy rate that’s higher than what’s available now. Refinancing can address both at once — not by adding new debt, but by restructuring what you already owe on better terms. What refinancing actually does Refinancing means replacing an existing loan with a new one — ideally at a lower rate, a longer term, or both. Done right, it can: Lower your monthly payment, freeing up cash for operations Reduce the total interest you’ll pay over the life of the loan Consolidate multiple debts (including higher-cost products like merchant cash advances) into one predictable payment Extend your term to match your actual cash flow cycle, instead of one that was forced on you at the time It’s not automatic savings. Refinancing has its own costs — sometimes prepayment penalties on the old loan, sometimes origination fees on the new one. The math has to work in your favor once those are factored in, which is exactly why this isn’t a decision to make off a headline about rate cuts. It’s a decision to make off your actual numbers. Questions worth asking before you refinance What rate are you actually paying right now? Not the rate you remember agreeing to — the effective rate today, including any fees baked into your payment structure. Is there a prepayment penalty on your current loan? If there is, it needs to be smaller than what you’d save by refinancing, or the move doesn’t pencil out. How much time is left on the loan? Refinancing a loan with six months left rarely makes sense. Refinancing one with three years left almost always deserves a second look. Is the debt you’re carrying high-cost, short-term financing? If part of your capital stack is a merchant cash advance or another fast-but-expensive product taken on during a tighter moment, that’s usually the first thing worth restructuring. When it’s not worth it Refinancing isn’t the right move for everyone, and I’d rather tell you that upfront than have you find out after signing something. If you’re close to paying off the loan, if the fees eat most of the savings, or if your business is in the middle of a stretch where taking on any new paperwork or underwriting review would be a distraction — it’s fine to wait. A lower rate that costs you operational focus at the wrong moment isn’t actually a win. The point isn’t to refinance for the sake of it. It’s to know where you stand, so the decision is yours to make with clear numbers in front of you — not a guess. Where to start If you’re not sure whether refinancing makes sense for your situation, the fastest way to find out is to actually run the numbers on what you’re carrying now against what’s available today. That’s the conversation I have with business owners every week — no pressure, no obligation, just a clear look at whether the math works in your favor. Every deal we help fund also contributes to Feeding America, so getting your capital structure right does a little more good along the way.
It Wasn’t One Big Check: Inside a Staged Growth Financing Story
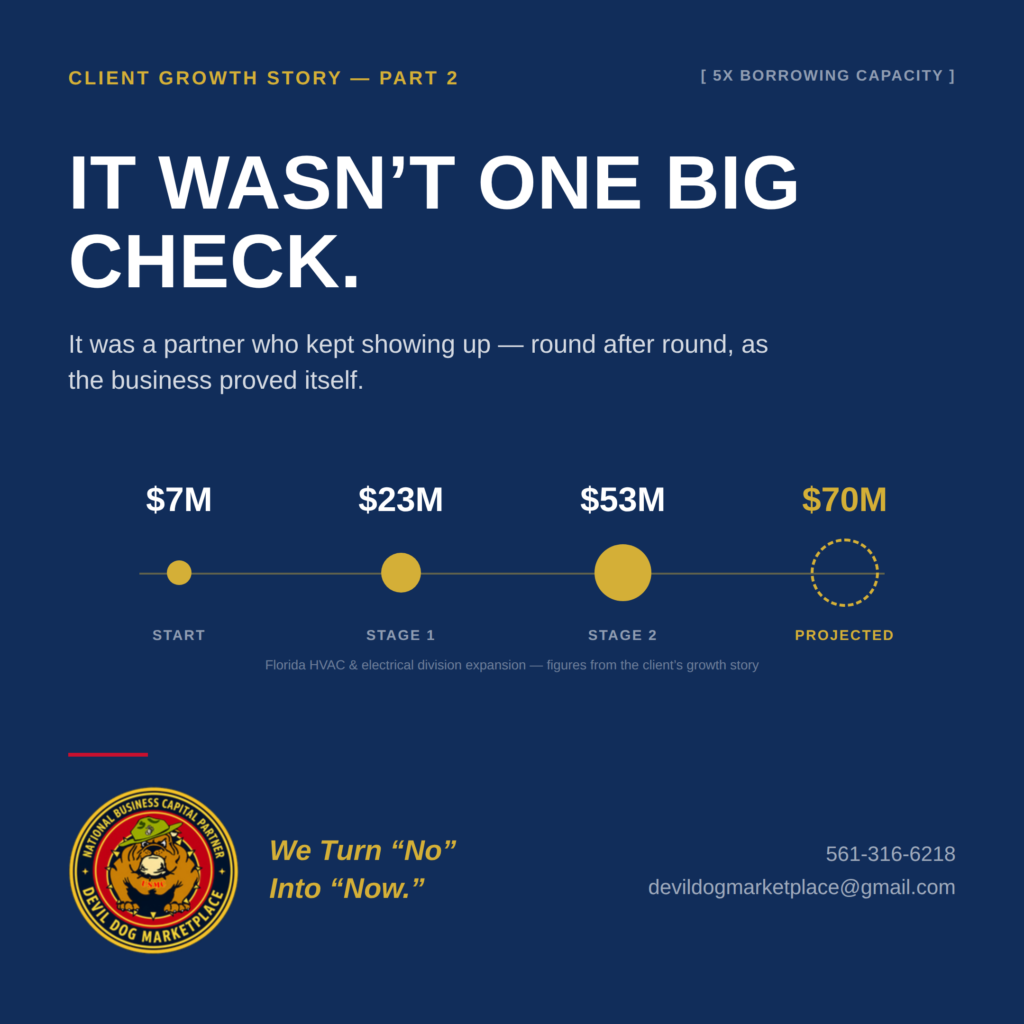
Last week I shared how a $250K loan got an HVAC owner through his slow season after a past bankruptcy had shut most lenders’ doors. What happened next is the part that stuck with me even more. Once stable, he wanted out of the seasonal cycle entirely — Florida HVAC means strong summers and quiet winters, no matter how well you run the business. He already had an electrical division. It just wasn’t big enough to carry the company through the slow months. Growing it meant more trucks, more electricians, real overhead before the revenue caught up. His lender didn’t just approve a lump sum — they staged it. Ten trucks, then twenty, then twenty more, each wave given time to settle before the next arrived. They even timed the purchases to capture a tax deduction on the equipment. The relationship scaled his borrowing capacity 5x over time. The business went from $7M to $23M to $53M, with $70M projected next. What gets me about this one is the sequencing. It wasn’t one big check — it was a partner who kept showing up as the business proved itself, round after round. If your business is working through a similar growth bottleneck, I’m glad to talk through what staged capital planning could look like for you.
How $900K in Cash Flow Financing Kept Supra’s NYC Expansion From Stalling Out
A brutal winter delayed construction on two new Supra locations by two months, creating $2 million in unplanned revenue loss. A $900,000 Cash Flow Financing facility from National Business Capital kept the restaurant group stable until both doors could finally open.