Equipment Financing 101: What Every Business Owner Should Know
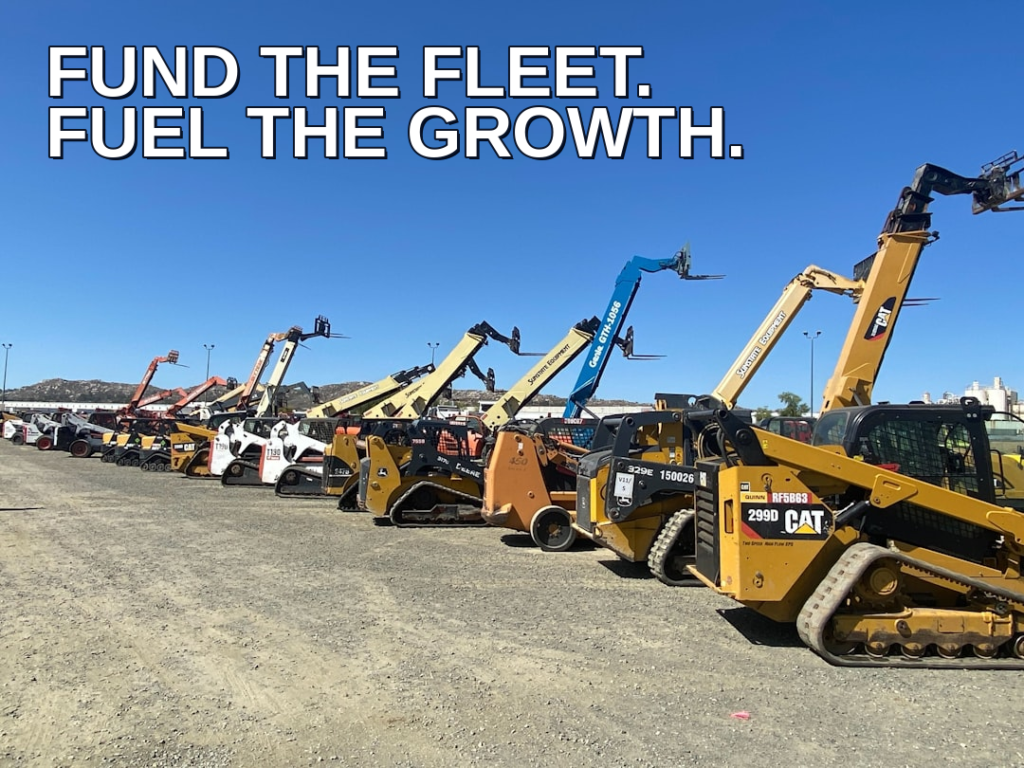
Equipment financing is one of the most misunderstood tools available to established businesses — and one of the most useful, especially if your industry runs on machines rather than desks. The Short Answer Equipment financing is a type of business funding used specifically to purchase, lease, or refinance the equipment a business needs to operate — skid steers, telehandlers, delivery vehicles, manufacturing machinery, medical equipment, kitchen equipment, and more. Instead of paying the full cost upfront, the business spreads payments over time, often using the equipment itself (or the cash flow it generates) as the basis for approval. How It’s Different From a Traditional Bank Loan Most business owners assume equipment financing works like a standard bank loan: submit years of financials, wait weeks, hope your credit score clears the bar. It often doesn’t work that way. Lenders in the equipment financing space frequently weigh a business’s cash flow, revenue trends, and the equipment itself more heavily than a traditional bank underwriter would. That doesn’t mean credit doesn’t matter — it does — but it’s typically one factor among several, not the single gate everything else has to pass through. Approval timelines can also move faster than a traditional bank loan, though actual speed and terms vary by lender, industry, and the specific equipment involved. The Three Common Structures Equipment loans — You finance the purchase and own the equipment outright once the term ends. Straightforward, and you build equity in the asset as you pay it down. Equipment leases — Lower monthly payments in exchange for not owning the equipment outright during the term. Some leases include a buyout option at the end; others don’t. A good fit for equipment that gets replaced or upgraded frequently. Sale-leaseback — If you already own equipment outright, you can sell it to a lender and lease it back, freeing up cash that’s currently sitting idle in a machine you already have. Why It Matters for Growth Here’s the practical reality: renting equipment for an extended job can cost more over time than financing the purchase — and at the end of a rental period, you own nothing. For businesses with a steady pipeline of contracts, financing the equipment outright (or through a lease with favorable terms) often makes more financial sense than renting project after project. It also solves a specific growth bottleneck: a business can be fully capable of winning more contracts but simply not have the machine on hand to take them on. Equipment financing exists to close that gap without draining the cash reserves a business needs for payroll, materials, and day-to-day operations. Who Typically Uses It Equipment-intensive industries lean on this type of financing most: construction and contractors, manufacturing and distribution, transportation and logistics, medical and dental practices, restaurants and food service, and franchise operations. If your business depends on physical equipment to generate revenue, it’s worth understanding as an option — even if you’re not actively shopping for a machine right now. The Bottom Line Equipment financing isn’t about qualifying for debt the way a bank loan works. It’s about matching the right funding structure to equipment that directly supports your business’s ability to take on more work. If you’re weighing a purchase, a lease, or wondering whether your current equipment could unlock cash through a sale-leaseback, that’s a conversation worth having — with no obligation attached to just exploring the options. Every business we help fund through National Business Capital also contributes to Feeding America, connecting business growth to a broader impact.
How Equipment Financing Helps Businesses Grow Without Draining Cash
Buying new equipment can be one of the biggest challenges for a growing business. Whether it’s construction machinery, medical devices, trucks, or manufacturing tools, the cost can strain cash flow. Equipment financing through National Business Capital gives business owners a way to get what they need now while paying over time — without putting daily operations at risk. What Is Equipment Financing? Equipment financing allows a business to purchase or lease equipment and pay for it in manageable monthly payments instead of one large upfront cost. The equipment itself often serves as collateral, which can make approvals easier compared to traditional loans. This option is ideal for businesses that want to: Upgrade outdated equipment Expand operations Increase productivity Preserve working capital How National Business Capital Helps National Business Capital works with a wide network of lenders to match businesses with equipment financing options that fit their situation. Instead of approaching one lender at a time, business owners can explore multiple options through a single process. Key benefits include: Fast approvals so equipment purchases aren’t delayed Flexible terms based on the business’s cash flow Financing for new or used equipment Support from experienced funding advisors This approach helps business owners focus on growth instead of paperwork. Who Equipment Financing Is Best For Equipment financing works well for many industries, including: Construction and contracting Transportation and logistics Medical and dental practices Manufacturing and industrial businesses Landscaping and service-based companies If equipment plays a critical role in delivering your product or service, financing can be a smart growth tool. Why Partners Recommend It For referral partners like CPAs, consultants, and financial advisors, equipment financing is a practical solution to offer clients who need assets but want to protect cash reserves. It supports business expansion without increasing unnecessary financial stress. Final Thoughts Equipment financing through National Business Capital gives businesses the ability to move forward confidently — acquiring essential tools while maintaining healthy cash flow. Instead of waiting or settling for outdated equipment, business owners can invest in what they need today and pay over time. Ready to explore your options? Reach out and let’s find the right equipment financing fit for your business.
Won a Big Contract? Here’s How to Fund It Before You Get Paid
You just landed one of the biggest projects your company has ever won. At first, it feels like a major victory. The contract is signed. The revenue looks great. Your team is excited. Then reality sets in. Before the first payment arrives, you need to hire additional workers, order materials, mobilize equipment, and cover payroll. The project may be profitable, but it requires cash today while customer payments may not arrive for weeks or even months. Many contractors discover that winning a larger project creates a new challenge: having enough working capital to get the job started. The Contractor Growth Challenge One of the biggest misconceptions in business is that profitability automatically means financial stability. For contractors, that’s often not the case. A company can be profitable on paper and still experience cash flow pressure because expenses happen long before project payments are received. Common upfront costs include: Payroll for field crews and supervisors Materials and supplies Equipment rentals and transportation Permits and mobilization costs Subcontractor deposits Fuel and operating expenses As project size increases, these costs increase as well. The question becomes: If a larger contract landed on your desk tomorrow, would your current cash flow support it? Why Many Contractors Turn Down Growth Opportunities When funding is needed, many business owners immediately think of traditional bank loans. Historically, banks often required collateral such as: Real estate Heavy equipment Vehicles Other business assets For some contractors, that works. For many others, it creates challenges. Some equipment may already be financed. Some owners prefer not to put personal assets at risk. Others simply do not want to wait through lengthy approval processes while a project timeline is moving forward. As a result, many contractors pass on opportunities that could help grow their business. A Different Approach to Business Funding Today’s funding landscape offers more options than many contractors realize. Rather than focusing only on collateral, many funding programs evaluate the overall strength of the business. Factors often include: Consistent Revenue Steady monthly revenue demonstrates that the company is operating successfully and generating income. Business Cash Flow Lenders want to understand how money moves through the business and whether there is capacity to support additional financing. Time in Business A proven operating history shows experience, stability, and the ability to manage projects successfully. Project Pipeline Upcoming contracts and future opportunities can help demonstrate growth potential and the purpose behind the requested funding. For contractors with strong operations and predictable revenue, these factors may be more important than the value of physical assets. The Best Time to Explore Funding The most successful contractors usually don’t wait until they are facing a cash crunch. Instead, they explore financing options before they need them. When a major project appears, they already understand: What funding options are available How much capital they may qualify for What documentation is required How quickly funding can be accessed Preparation creates flexibility and confidence when opportunities arise. Key Takeaways Cash Flow Matters More Than Profit A profitable project can still create financial strain if expenses come due before customer payments arrive. Growth Requires Capital Larger contracts often require additional labor, materials, equipment, and working capital. Traditional Banks Are Not the Only Option Modern funding solutions may focus on business performance, revenue, and future opportunities rather than solely on collateral. Your Future Work Has Value A strong pipeline of contracts can demonstrate business strength and growth potential. Plan Before You Need Funding Understanding your options ahead of time allows you to move quickly when the right opportunity appears. Final Thoughts Many contractors don’t struggle because they lack profitable work. They struggle because growth requires cash before customers pay. The good news is that funding options have evolved. Business owners today may have access to solutions designed specifically for established companies that need capital for expansion, equipment, acquisitions, payroll, inventory, or large projects. If you’re wondering whether your business could qualify for funding, a simple conversation can often provide clarity without any obligation or pressure. Learn More: https://www.youtube.com/watch?v=SWaeEqyuvSU Devil Dog Marketplace, Proud Partner of National Business Capital Website: https://www.devildogmarketplace.com LinkedIn: https://www.linkedin.com/in/michaelfieger/ National Business Capital: https://www.nationalbusinesscapital.com Funding Application: https://www.nationalbusinesscapital.com/apply-now/?ref=5466172