Cash Flow Financing 101: What It Is and When It’s the Right Move
Quick answer: Cash Flow Financing is short-term capital sized around your actual cash conversion cycle. When revenue is steady but collections are slow, it’s often a better fit than a traditional multi-year loan. Not every business needs a term loan. If your revenue is steady but your collections are slow (Net 60, Net 90, or longer), the right tool is often Cash Flow Financing, not a traditional multi-year loan. What it is Cash Flow Financing is short-term capital sized and structured around your business’s actual cash conversion cycle, not a fixed collateral value or a rigid five-year amortization schedule. It’s designed to bridge the exact gap that trips up a lot of otherwise-healthy businesses: the time between when you have to pay (payroll, materials, vendors) and when you actually get paid (milestone billing, invoice terms, seasonal collections). Who tends to qualify fastest Businesses with predictable deposits and repeatable revenue patterns, even if their paperwork isn’t perfectly polished. Underwriting for this type of financing looks less at a stack of documentation and more at what your bank statements actually show: consistent cash moving through the business. That’s a meaningful distinction. A lot of business owners assume a less-than-perfect credit file or incomplete paperwork disqualifies them. In reality, strong, consistent cash flow can get you funded faster than a business with cleaner paperwork but choppier revenue. When it beats a term loan If your funding need is tied to a recurring, cyclical gap, Cash Flow Financing is usually the more natural fit than a long-term, fixed-structure loan. Think of: Contractors waiting on milestone payments Seasonal businesses ramping up inventory Service businesses billing on Net 60/90 If you’re not sure which type of capital actually fits your situation, that’s a conversation worth having before you apply for anything. We’re happy to walk through it with you. Not sure which type of capital fits? Let’s talk before you apply for anything. No pressure and no pitch. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
Why Your Fastest Deals Need a Fast-Capital Partner: A Guide for M&A Advisors and CFOs
Quick answer: When bank underwriting takes six to eight weeks, good deals stall. A fast-capital partner lets advisors bring clients a funding decision in days instead of months. M&A advisors, private equity professionals, investment bankers, CPAs, fractional CFOs, and business consultants all share the same frustration: a great deal, ready to close, stuck waiting on traditional bank underwriting. Why bank timelines hurt deals Bank timelines weren’t built for deal urgency. Six to eight weeks of underwriting is standard. Meanwhile, sellers get impatient, buyers find other options, and the window on a good deal can close before the bank finishes its paperwork. What a fast-capital partner changes That’s the gap a fast-capital partner fills. When you can bring your client a funding decision in days instead of months, you aren’t just solving a cash flow problem. You’re the reason the deal actually closed. How we work alongside advisors We work with advisors, not instead of them: 75+ lending relationships Funding from $1M to $75M Decisions that don’t wait on a committee calendar You stay the trusted advisor. We’re the fast option in your back pocket when timing is the only thing standing between your client and a signed deal. Tired of watching good deals stall? Let’s talk about how a faster capital relationship fits into your process. No pressure and no pitch. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
Bank Said No? Here’s Why That’s Not the End of Your Funding Story
Quick answer: A bank decline usually just means one lender’s box didn’t fit your business. It rarely means your business isn’t fundable. For a lot of business owners, a bank decline feels final. In our experience, it’s rarely the end of the story. Two examples A fragrance manufacturer. Their senior lender turned them down right as major retailers placed enterprise-level orders, exactly the wrong moment for a “no.” We stepped in with $15M in strategic capital so production never stopped. A trucking company. They needed cash fast to fund two new contracts, and their bank passed. We didn’t. They had $300K in hand within 48 hours. Why a different kind of lender can say yes Banks lend on rules: fixed formulas, rigid credit boxes, slow committees. We lend on reality: your cash flow, your growth trajectory, and where your business is actually headed. That’s why we work with 75+ lenders instead of one, so there’s almost always a fit somewhere. What to do next If your bank has said no, or you’re worried they will, that doesn’t mean your growth plans are on hold. It usually means it’s time for a different kind of conversation. Semper Fi,Michael FiegerBusiness Funding Advisor, Partner of National Business Capital Let’s talk it through No pressure and no pitch. Tell me what you’re working on, and I’ll tell you what’s realistic. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
Revo Roofs Case Study: $400K in Cash Flow Financing Through an Ownership Transition
Quick answer: Revo Roofs, a roofing contractor generating over $1M in monthly revenue, needed working capital during an ownership transition. $400K in Cash Flow Financing kept operations running while receivables caught up. Client spotlight Revo Roofs is a leading roofing contractor achieving over $1M in monthly revenue. They execute large residential and commercial roofing projects, with seamless coordination and financial discipline at the core of their operations. A strategic transition In 2025, Revo Roofs set out to strengthen leadership and financial management. The owner reacquired full control by completing a partner buyout, and a new CFO was appointed to revamp the financial infrastructure, paving the way for future growth. The challenge During the ownership transition, the company wisely refocused on completing existing projects to stabilize under the new leadership. That was the right move, but it temporarily eased incoming receivables. The solution To bridge the gap, National Business Capital provided $400K in Cash Flow Financing. The funding ensured: Essential working capital for payroll and operational expenses Support for active project materials Flexibility as receivables from completed jobs were collected Alignment with their refined financial strategy The result With capital in place, Revo Roofs maintained uninterrupted operations while solidifying its financial restructuring. With stronger ownership and oversight, the company is positioned to reignite its project pipeline and drive future growth. Let’s talk it through No pressure and no pitch. Tell me what you’re working on, and I’ll tell you what’s realistic. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
Capital Shouldn’t Be the Reason Growth Stalls
Thriving businesses don’t always need more opportunities — they need the right capital at the right time to soar. See how Devil Dog Marketplace’s streamlined process gets you funded quickly and efficiently.
Empower Your Business: Tailored Loans for Women Entrepreneurs
Quick answer: The Empowerment Loan is designed exclusively for women-owned businesses, offering flexible financing for hiring, cash flow, equipment, payroll, or growth, with funding available in as little as 24 hours. Women entrepreneurs deserve funding solutions built for the way they do business. The Empowerment Loan is designed exclusively for women-owned businesses, offering flexible financing to help you hire employees, manage cash flow, purchase equipment, cover payroll, or invest in growth opportunities. What you get Funding available in as little as 24 hours Minimal paperwork and a streamlined process A dedicated Business Financing Advisor throughout the process No collateral required No minimum FICO score requirement Available across most industries To qualify Business must be at least 51% woman-owned Minimum 6 months in business At least $250,000 in annual gross revenue Financing options include Business Loans: flexible terms and funding up to $5 million Business Line of Credit: access working capital when you need it SBA Financing Solutions: easier qualification requirements and faster funding than many traditional lending options At National Business Capital, we work with a nationwide network of lending partners to help women business owners access the capital they need to grow with confidence. Michael FiegerBusiness Funding Advisor, Partner of National Business Capital Ready to explore your options? No pressure and no pitch. Tell me what you’re working on, and I’ll tell you what’s realistic. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
How To Get Fast Business Loans Up To $75 Million (Even When Banks Drag Their Feet)
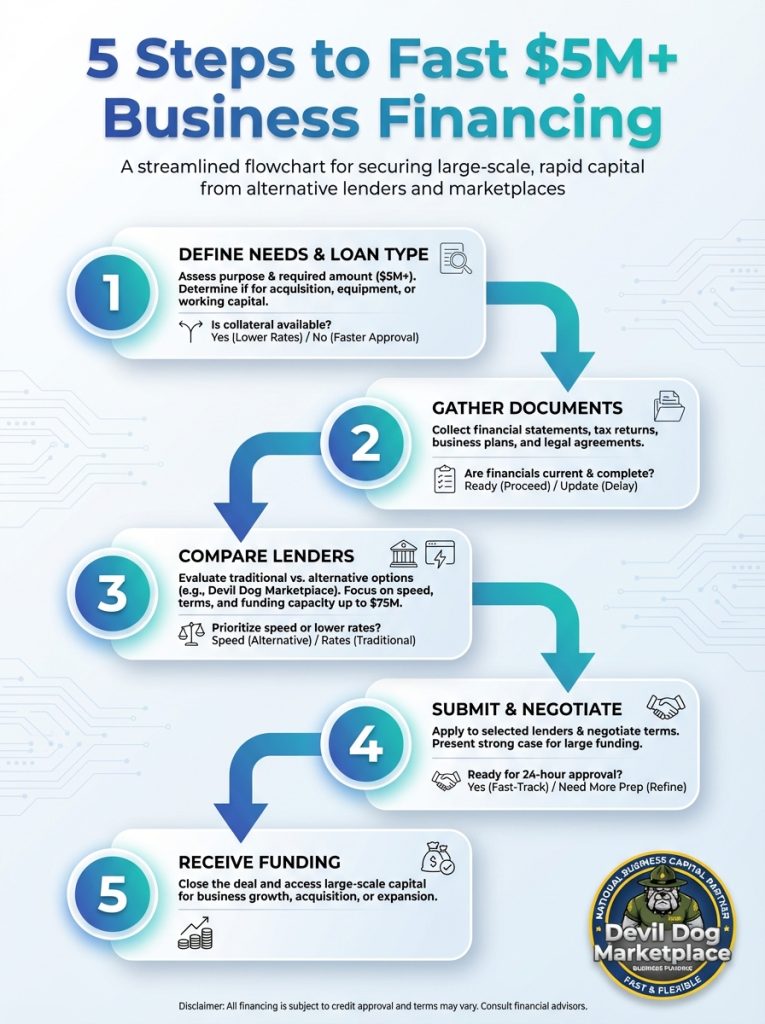
Most growing companies do not realize that nearly all banks will lend at least $1 million and about half will go up to $3 million, yet many still get stuck in slow processes or flat-out declines when they need funding fast. We built a business capital marketplace so you can move past those delays and access large business loans, flexible funding solutions, and true partnership when you are aiming for $1 million to $75 million in growth capital. Key Takeaways Question Answer How fast can I get a $5 million business loan? With a prepared financial package, we often see approvals for $1M+ in a few days and in some cases funding within 24 hours from alternative business lenders through our funding solutions. What is a business capital marketplace? It is a centralized platform where we bring together many alternative business lenders so you can compare term loans, lines of credit, equipment financing, and acquisition funding in one place instead of applying one by one at banks. Can I get business capital without collateral? Yes, we regularly see unsecured working capital loans and revenue based funding, especially for businesses with strong cash flow and clear plans for large business growth. Do you fund only local companies in Florida? We support companies nationwide, but we have deep experience with business loans in West Palm Beach, South Florida commercial loans, and deals across Palm Beach County’s active real estate and construction markets documented throughout our Devil Dog Marketplace platform. What types of deals are best for $1M+ fast business funding? Business acquisition financing, equipment financing above $500K, large working capital lines of credit, and construction or manufacturing expansions where timing is critical. Do you work with veterans? Yes, as a veteran-led team we take business loans for veterans seriously and help owners understand both marketplace options and government-backed programs, starting with a simple conversation on our contact page. 1. What Large Business Loans Up To $75 Million Really Look Like When you hear “business loans up to $75 million,” it can sound like something reserved only for massive corporations. In reality, we see mid-market companies, fast growing regional brands, and family-owned operations qualify for large business loans when they have solid revenue, clear uses for capital, and realistic repayment plans. From $1M Fast Funding To $75M Strategic Capital On our platform, lenders commonly provide flexible term loans, large working capital facilities, and acquisition lines that range from $1 million to $75 million. These deals often blend multiple structures, like a core term loan for a business acquisition plus a revolving line of credit for working capital. Why Many Owners Outgrow Traditional Banks Banks can be a fit for some needs, but they are often slower and more rigid when businesses want to move on an acquisition or expansion quickly. We positioned our business capital marketplace specifically as an alternative to bank business loans when speed, flexibility, and creative structures matter more than a single low advertised rate. Real Example: Multi-Million Dollar Working Capital For Growth One of our featured stories highlights a company that secured a seven-figure working capital loan to support rapid expansion after banks hesitated because of previous losses. By focusing on forward-looking cash flow and contracts, not just historical hiccups, our lending partners were able to fund fast and keep the growth plan moving. 2. How A Business Capital Marketplace Beats One-Size-Fits-All Lending A business capital marketplace is built around one idea, which is that no single lender is the right answer for every deal. Instead of pushing you toward one product, we match your business with a curated set of alternative business lenders that specialize in your size, industry, and purpose. Centralized Access To Multiple Lenders We work with a network that can fund up to $75,000,000 in business capital, with programs for term loans, lines of credit, and specialized equipment financing over $500K. You complete one clear application, then our advisors help you compare structures, rates, and timelines so you can choose your best fit. Everything Banks Don’t Offer Where banks tend to rely heavily on rigid underwriting and collateral, alternative lenders can lean into cash flow, contracts, and future potential. That makes it easier to secure business capital without collateral, especially for working capital loans and revenue based terms. Support, Not Sales Pressure We approach each request like a mission brief: clear questions, straight answers, and no pressure. Our advisors help you understand tradeoffs between term loans, short term working capital, and lines of credit so you stay in control of your financing strategy. 3. Fast Business Funding $1 Million+ And 24 Hour Approvals Speed of funding is not a luxury when payroll, acquisition timelines, or equipment deliveries are on the line. That is why fast business funding for $1 million and above is one of the core pillars of our marketplace. How To Get A $5 Million Business Loan Fast If you want to know how to get a $5 million business loan fast, the key is preparation. We help you organize current financials, a clear use of funds, projections, and any contracts or LOIs so lenders can underwrite in hours instead of weeks. What 24 Hour Approval Really Means When we say business funding with 24 hour approval, we are talking about conditional approvals or offers from flexible alternative lenders, often followed by funding within a few days. For repeat clients with strong track records, we sometimes see money wired in less than 24 hours once documentation is complete. Real-World Example: One Million Business Loan Payment In our “One Million Business Loan Payment” feature, we highlight a company that secured a seven figure facility, used it to drive growth, then repaid on schedule and accessed additional funding later. That kind of long term funding relationship is possible when a lender priorities transparency, performance, and communication over one-time transactions. Discover a 5-step path to fast $5M+ financing for large businesses. Learn how alternative lenders, equipment financing, and working capital can accelerate growth in
Unlocking Growth Potential Through Capital: What You Need to Know
The companies that grow intentionally don’t wait for cash problems to show up. Discover why “Strategic Red” — deliberate, planned capital use — is the difference between surviving and thriving.
7 Steps to Scale Your Construction Business Past $10M
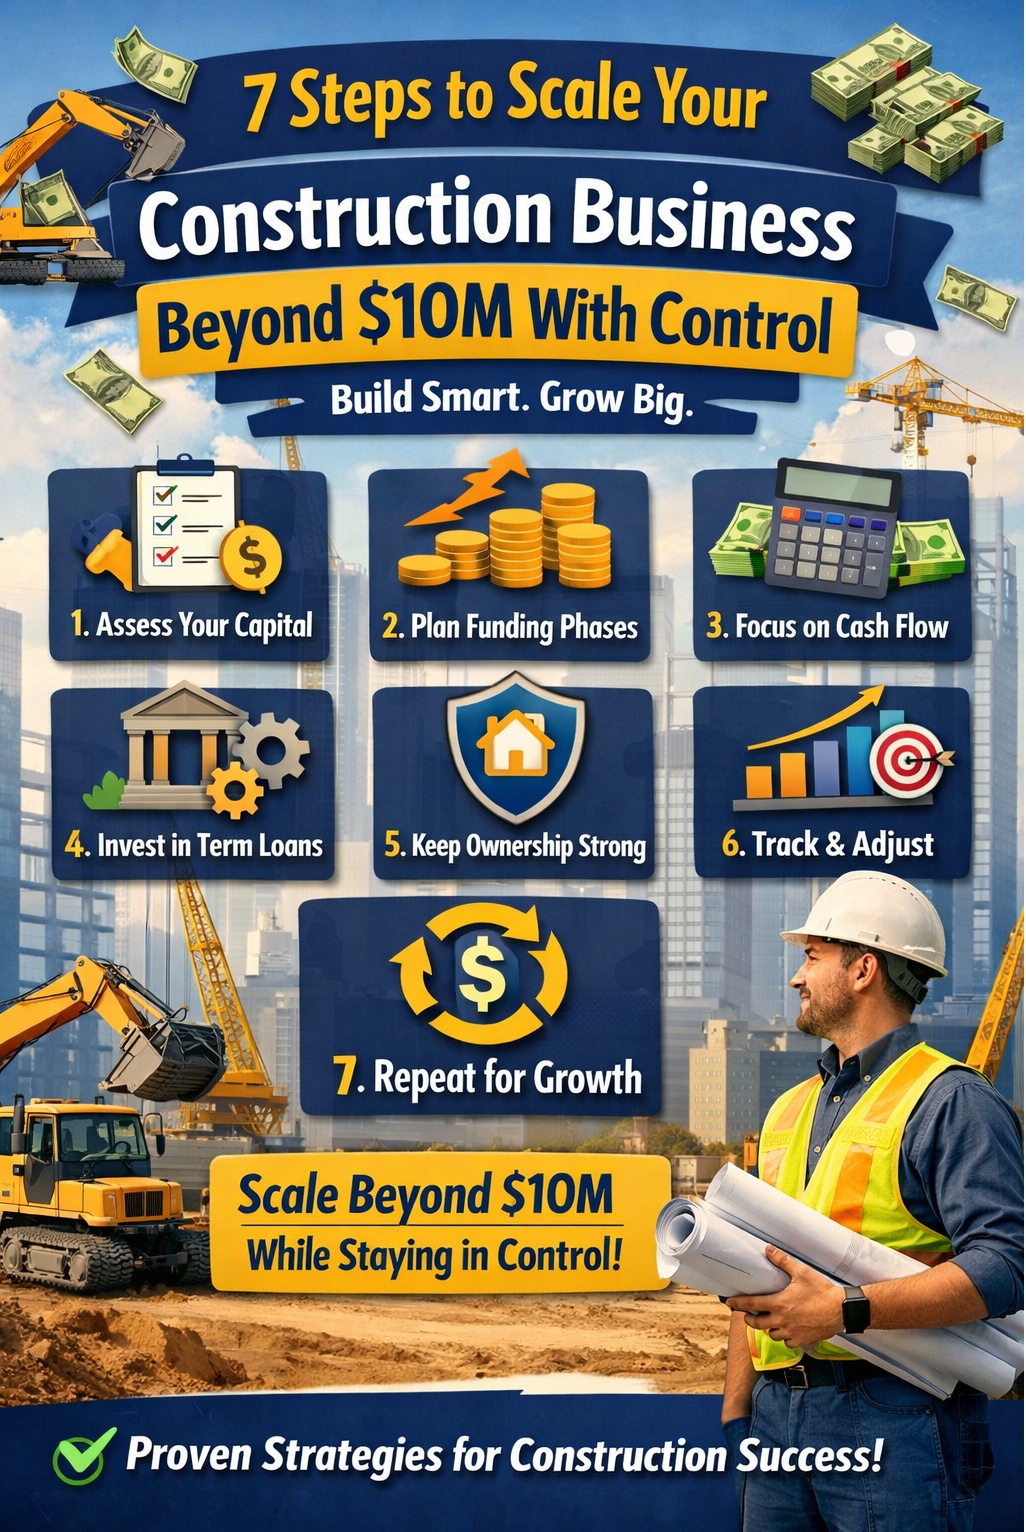
Hitting the $10M mark in construction isn’t about landing one big project—it’s about having the right capital plan in place. If you’ve ever felt stuck, watching opportunities slip by because you didn’t have cash or equipment ready, you’re not alone. Many contractors assume that securing funding is a one-time fix. In reality, without a structured funding approach, extra money can create more stress than solutions. Brasfort*, a construction firm we partnered with, faced this exact challenge. They wanted fast growth—but growing without a plan can easily overwhelm a business. Over 3.5 years, they carefully deployed nearly $5 million across ten strategic funding phases, each aligned with a specific operational goal. The payoff? Revenue doubled, margins improved, equipment ownership increased, and operational control stayed firmly in their hands. In this article, you’ll discover 7 actionable steps to organize funding like Brasfort, helping your construction business surpass $10M while maintaining ownership, control, and clarity. Step 1: Take a Clear Look at Your Current Capital Before pursuing more funding, you need to know exactly where you stand financially. Consider: How much debt is already on the books? Which assets are leased, and which are owned? Where are your cash flow gaps in the short and long term? Why it matters: Without understanding your starting point, you risk borrowing money that doesn’t solve the right problem. Brasfort documented every asset, liability, and project expense, giving us a clear foundation for planning future rounds. Actionable Steps: List all current assets and liabilities. Highlight recurring cash shortfalls. Rank funding priorities based on impact and urgency. Step 2: Plan Funding in Phases Rather than seeking a single large loan, split funding into phases tied to operational objectives. Brasfort implemented 10 rounds of Cash Flow Financing, each supporting equipment, projects, or internal systems. Benefits of phased funding: Limits the risk of over-borrowing Ensures capital supports real operational needs Makes business growth predictable and repeatable How to start: Identify 3–5 growth objectives for the next 1–3 years. Assign a dedicated funding round to each objective. Align repayment schedules with project timelines. Step 3: Focus on Cash Flow, Not One-Off Jobs Funding is most effective when it’s strategically planned, not just reactive. Many companies borrow only when a big project arises, which creates stop-and-go growth. Brasfort’s approach: Rolling Cash Flow Financing allowed them to be ready for projects at any time No downtime between jobs, fewer missed opportunities How to apply this: Maintain a 3–6 month funding reserve Keep a buffer for equipment and unexpected project needs Avoid using borrowed money for unrelated expenses Step 4: Use Term Loans for Long-Term Improvements Short-term loans solve immediate problems—but strategic, long-term growth requires deliberate investment. Brasfort used a Term Loan to strengthen internal systems, making operations scalable. Actionable Steps: Identify gaps in core operations (project management, finance systems, HR, ERP) Estimate how much capital is needed to address each Invest in solutions that improve efficiency and sustainability, not just revenue Step 5: Keep Ownership at the Center Growth shouldn’t mean losing control of your business. Brasfort structured each round so funding supported operations without diluting ownership. Tips to maintain control: Use debt rather than equity for operational funding Align borrowing with cash flow, not convenience Set clear repayment plans to avoid surprises Step 6: Track Outcomes and Adjust Every funding phase should have measurable goals. Brasfort tracked: Revenue growth Margin improvement Equipment ownership Strength of internal systems Actionable Steps: Assign KPIs to each funding round Conduct monthly or quarterly reviews Adjust future funding based on results, not assumptions Step 7: Make Funding a Repeatable Practice Sustainable growth comes from turning funding into a predictable, repeatable process. Brasfort’s phased plan became a blueprint for consistent, scalable expansion. How to implement: Document every funding round and its purpose Create standard procedures for evaluation and approval Share lessons internally to improve future planning Conclusion Scaling a construction business past $10M is less about chasing every job and more about structuring capital strategically. Brasfort’s success proves: Multi-phase funding reduces risk and supports sustainable growth Aligning funding with operational goals strengthens ownership and control Documented processes make borrowing repeatable and predictable Provocative Question: Which area—capital, operations, or ownership—is holding your construction business back from $10M? Ready to build a capital strategy that fuels growth? Refer a client to National Business Capital Partner Michael Fieger today and help them scale with confidence. Let’s talk it through No pressure and no pitch. Tell me what you’re working on, and I’ll tell you what’s realistic. Talk With MichaelRead the Funding FAQ Or call 561-316-6218
Strong Revenue but No Cash? How Advisors Solve Payroll Problems
Ever Had a Client Who Looks Great on Paper- but Is Scrambling to Make Payroll? Quick summary: Some businesses look successful on paper but still struggle to pay employees. This happens when cash flow can’t keep up with growth. Smart advisors help clients spot these gaps early and use flexible funding to stay stable. This happens more often than most people think. A business can look very successful from the outside. Sales are high. Revenue is growing. Reports look strong. But behind the scenes, the owner is worried. Cash is tight. Payroll is stressful. Bills are piling up. If you’re a CPA or business advisor, you’ve likely seen this before. Let’s break it down in a simple way — why this happens, why banks often don’t help, and what smart advisors do instead. Revenue and Cash Flow Are Not the Same This is the biggest misunderstanding in business. Revenue is how much money a business earns. Cash flow is how much money is actually available right now. A business can make a lot of money on paper but still struggle to pay employees. Why? Because cash can get stuck. Common Reasons Cash Flow Gets Tight Even healthy businesses can run into cash problems because of: Customers who pay late Seasonal ups and downs Hiring new employees too fast Buying equipment or inventory Growing faster than cash can support Payroll doesn’t wait. Rent doesn’t wait. Vendors don’t wait. A Real Example From a CPA Partner A CPA reached out last month about a client. The business was doing record sales. But cash flow was still negative. Customers were slow to pay. Growth costs were adding up. Payroll was becoming stressful. The numbers looked fine. The stress was very real. Why Banks Often Don’t Help in Time When cash flow is tight, banks are usually slow. They often require: A lot of paperwork Strong credit history Long approval times By the time a bank gives an answer, payroll is already due. That delay can hurt the business. A Better Option: Flexible Business Funding Instead of sending the client to a bank, we focused on speed and flexibility. The goal was simple: Cover payroll Keep the business running Give customers time to pay their invoices Reduce stress for the owner The funding helped bridge the gap. Employees were paid. The business stayed open. Why This Matters for Advisors Business owners don’t just want reports. They want peace of mind. Advisors who help protect cash flow: Build trust Strengthen relationships Become long-term partners Helping a client survive a tough moment matters more than any spreadsheet. Simple Questions Advisors Should Ask These questions can reveal problems early: Do you always have enough cash for payroll? What happens if customers pay late? How many weeks could you operate if cash slowed down? Do you have a backup plan for cash flow gaps? Simple questions can prevent big problems. The Bottom Line Growth is exciting. But growth without cash can be dangerous. Cash flow keeps businesses alive. Advisors who help clients stay liquid, calm, and prepared become trusted partners — not just service providers. So here’s the big question: When cash flow gaps show up, what’s your go-to move? What This Means for You If you work with business owners, cash flow issues will come up — even when revenue looks strong. Having a plan before payroll stress hits can: Protect your client Reduce panic decisions Strengthen long-term trust If you’re an advisor who wants a faster, simpler way to help clients bridge cash flow gaps, flexible funding options can make a real difference. Ready to build a capital strategy that fuels growth? Refer a client to National Business Capital Partner Michael Fieger today and help them scale with confidence. Let’s talk it through No pressure and no pitch. Tell me what you’re working on, and I’ll tell you what’s realistic. Talk With MichaelRead the Funding FAQ Or call 561-316-6218